
How to Spot Fake Bank Statements: 12 Signs and How to Verify Them
12 signs of a fake or edited bank statement, how to verify one with the bank, and what automated checks catch, from a tool that has scored 1.49 million statements. For lenders, underwriters, and landlords.
A fake bank statement is a statement that has been fabricated from scratch or edited to change balances, deposits, names, or dates, usually to pass a loan, rental, or income check. The fastest way to spot one is to check that the opening balance plus deposits minus withdrawals equals the closing balance, then inspect the file itself for signs of editing. To verify a statement, confirm it with the bank through contact details you found independently, or use account data that comes straight from the bank.
This guide is written for underwriters, lenders, landlords, and anyone else who has to decide whether a statement is real. It covers the checks you can run by hand and what we have learned from scoring 1.49 million statements automatically. To screen a PDF in seconds instead, use a fake bank statement detector.
While you are here
Catch anomalies before you sign off
Manual PDF review misses things, especially at page 80. DocuClipper's analyzer flags edits, suspicious patterns, and anomalies so your team focuses on the right pages first.
Can fake bank statements be detected?
Yes, most of the time. Editing a statement convincingly is harder than it looks, because a real statement is internally consistent: every transaction feeds a running balance, every period links to the next, and the PDF carries traces of the system that produced it. Changing one number without breaking something else is difficult. Fabricated statements made from templates also tend to repeat the same mistakes.
No single check is conclusive, so combine the signs below with verification at the source.
12 signs of a fake or edited bank statement
The signs fall into four groups: the numbers, the document, the applicant's details, and the file itself. A real statement passes all four. An edited one usually fails at least one.
| # | Sign | What to check |
|---|---|---|
| 1 | The statement does not reconcile | Opening balance + credits - debits = closing balance |
| 2 | Running balances jump | Each line's balance follows from the one before |
| 3 | Periods do not link | Each closing balance is the next opening balance |
| 4 | Too many round numbers | Deposits look like real, irregular amounts |
| 5 | Inconsistent fonts or alignment | Amounts sit on the same baseline, in the same font |
| 6 | Layout differs from the bank's current format | Compare with a known-genuine statement |
| 7 | Errors a bank would not make | Spelling, bank address, impossible dates |
| 8 | Missing pages | "Page 2 of 4" really has four pages |
| 9 | Deposits that do not match stated income | Pay stubs and tax forms agree with the deposits |
| 10 | No ordinary spending | Utilities, groceries and card payments are there |
| 11 | Account holder details differ | Name, address and account number match other documents |
| 12 | The PDF was changed after the bank created it | Producer, creation and modification dates |
1. The statement does not reconcile
Opening balance plus credits minus debits should equal the closing balance. If a deposit was inflated or added, the math usually breaks unless the forger also edited the balances.
2. Running balances jump
On statements with a running balance column, each line should equal the previous balance plus or minus that transaction. A balance that jumps without a matching transaction points to an edited amount.
3. Periods do not link
Each statement's closing balance should equal the next statement's opening balance. Gaps or mismatches between months are a strong signal, which is why asking for consecutive months is worth it.
4. Too many round numbers
Real accounts have irregular amounts. A run of round deposits, especially payroll-like deposits, deserves a closer look.
5. Inconsistent fonts or alignment
Edited amounts often sit slightly off the baseline, use a different font size or weight from the rest of their row, or break the column alignment.
6. Layout differs from the bank's current format
Compare with a known-genuine statement from the same bank and period. Old logos, outdated disclosures, or a different footer suggest a template.
7. Errors a bank would not make
Spelling mistakes, a wrong bank address, impossible dates such as February 30, or a statement period that does not match the bank's cycle.
8. Missing pages
Page "2 of 4" with only three pages, or missing disclosure pages, can hide removed transactions.
9. Deposits that do not match stated income
Employer names, pay frequency, or amounts that differ from pay stubs or tax forms.
10. No ordinary spending
A primary account with no utility, grocery, or card payments may not be the account it claims to be.
11. Account holder details differ
Name, address, or account number that does not match other documents in the file.
12. The PDF was changed after the bank created it
A bank generates a statement in one pass. A file saved again in a PDF editor, with a modification date long after its creation date or edits appended to the original, has been touched since it left the bank.
Check the file, not just the page
A PDF downloaded from a bank carries metadata about the software that created it and when. Edited statements often show:
- A producer such as a word processor, image editor, or online PDF editor instead of the bank's document system.
- A modification date well after the creation date.
- Edits saved on top of the original file, which leave the earlier version inside the PDF.
- Two sets of metadata in the same file that disagree about which software made it.
- Mixed or substituted fonts, or text layered over an image of the original.
Scans and screenshots remove most of this evidence, which is why asking for the original download matters.
How to verify a bank statement
- Get the original file. Ask for the PDF exactly as downloaded from online banking, not a scan, screenshot, or re-saved copy.
- Run the math. Check that every statement reconciles and that closing balances carry forward to the next period's opening balance.
- Inspect the document. Review layout, fonts, dates, account details, and transaction patterns against the signs above.
- Check the file. Open the document properties and look at the producer and the creation and modification dates.
- Verify with the source. Contact the bank through an independently sourced phone number with the applicant's written authorization, or use bank-sourced account data. Never use the phone number or email printed on the statement you are checking.
- Document the decision. Record what you checked, what you found, and why you accepted or escalated the file.
Bank-sourced data, such as a verification of deposit request or a read-only account connection the applicant authorizes, is stronger evidence than any document, because the applicant never handles it.
Put it into practice
A checklist only works when nobody's tired
Structured signals give managers a repeatable first pass. Reviewers get consistent results whether they're looking at page 3 or page 300.
How to tell if a tenant's bank statement is fake
Rental applications are one of the most common places edited statements turn up, usually with an inflated paycheck or balance to clear an income requirement. The checks are the same as above, with three habits that matter most for leasing teams:
- Ask every applicant for the PDF from online banking. A screenshot or phone photo loses the edit history and metadata, so only the math can be checked. Make the original PDF part of the standard application requirements.
- Ask for consecutive months. Two or three statements in a row let you confirm that each closing balance carries into the next opening balance, which a forger has to fake consistently across every file.
- Check every applicant the same way. Fair housing rules apply to how you screen, so run every file through the same checks and verify a suspicious statement with the bank before you decline anyone.
Property managers reviewing many applications can run these checks in software: see tenant bank statement verification for how each statement gets an authenticity score, how to verify income from the same statements, and how that compares with screening tools built into the rental application.
Using a fake bank statement detector
Manual review does not scale to a high volume of applications. A fake bank statement detector runs the first pass in seconds, on every page, the same way every time. DocuClipper's fake bank statement detector checks each statement for:
- Math: whether the opening balance, transactions, and closing balance add up.
- Pasted-in amounts: figures whose size does not match the rest of their row, with the page and position.
- Edit history: a PDF editor named in the file, changes after the bank created it, edits saved on top of the original, and metadata that disagrees with itself.
- Layout: whether the file matches statements already known to be authentic for that bank.
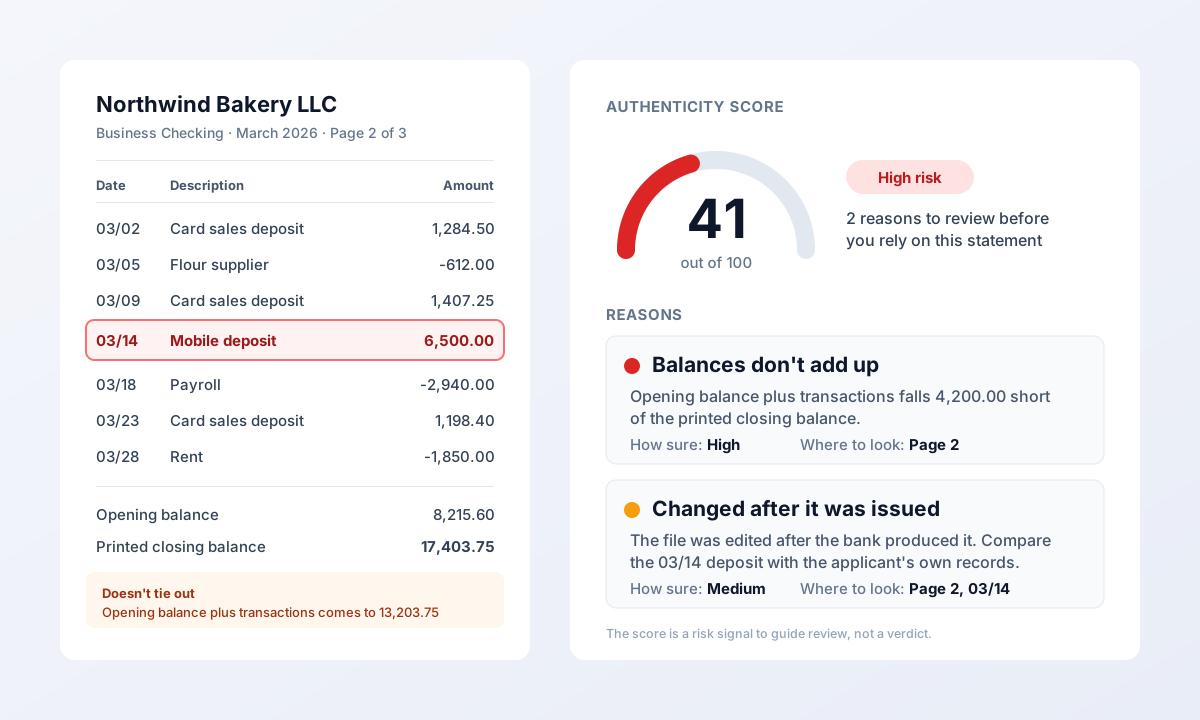
The result is a 0-100 authenticity score with the reasons behind it, so a reviewer can confirm or clear a file quickly. For how the score is calculated, see understanding bank statement fraud detection. Lenders who also need income figures can pair it with bank statement income verification.
What 1.49 million scored statements taught us
DocuClipper has given 1.49 million bank statements an authenticity score since April 2025. Three lessons carry over to manual review:
- An unfamiliar-looking statement is not a fake. Banks change their statements, and a new version or a small bank can look unusual next to the ones you know. Treat it as a reason to compare, not to reject.
- Unbalanced math has innocent causes too. Missing pages, partial exports, and statements cut off mid-period break the balance check as reliably as an edited deposit. Ask for the complete file before drawing conclusions.
- A file changed after the bank issued it deserves the closest look. Genuine bank PDFs are generated once. When a statement has been edited since, ask for the original download from the bank.
Want to see it on a statement you are unsure about? The 14-day free trial includes fraud detection, with no credit card.
Is it illegal to fake a bank statement?
Yes. Using a falsified bank statement to obtain a loan, lease, benefit, or visa is fraud in the US and most other countries, and submitting one to a federally insured lender can be a federal crime. Websites that sell "novelty" statements do not make their use legal.
For background on what a genuine statement contains, see what is a bank statement and how to read a bank statement.
FAQ
How can you tell if a bank statement is fake?
Check that the balances reconcile and carry forward between periods, then look for inconsistent fonts or alignment, an outdated layout, round-number deposits, missing pages, signs the PDF was edited after the bank created it, and details that do not match the applicant's other documents. Confirm with the bank when anything looks off.
Can a PDF bank statement be edited?
Yes, with any PDF editor, which is why the file matters as much as the page. Editing usually leaves traces: an editor named as the producer, a modification date after the creation date, edits saved on top of the original, or amounts in a slightly different font size.
Can fake bank statements be verified?
Yes. Contact the bank through a phone number you found independently, with the account holder's authorization, or use bank-sourced account data. Do not rely on contact details printed on the statement.
What is a fake bank statement detector?
Software that screens statements for signs of editing, such as balances that do not reconcile, pasted-in amounts, PDF edit history, and a layout that does not match known-genuine templates. It flags files for review rather than proving fraud.
Is there a free fake bank statement detector online?
DocuClipper's fraud detection is included in the 14-day free trial, with no credit card. Upload the original PDF to get an authenticity score and the signals behind it. Photos and screenshots get only the balance check, since PDF metadata does not survive in an image.
How do landlords check if a bank statement is fake?
Ask for the original PDF from online banking and for consecutive months, check that the balances reconcile and carry forward, then look for signs the file was edited after the bank issued it. Verify anything suspicious with the bank, with the applicant's authorization, and run every applicant through the same checks. Leasing teams with many applications can automate the first pass with tenant bank statement verification.
Can a legitimate statement be flagged as suspicious?
Yes. Scans, re-saved PDFs, print-to-PDF workflows, and new bank templates can trigger flags. Review the individual signals and verify with the bank before rejecting an applicant.
Is it illegal to use a fake bank statement?
Yes. Submitting a falsified statement to obtain credit, housing, or benefits is fraud and can be prosecuted.
Written by the DocuClipper editorial team. Last updated October 28, 2026. General information, not legal or tax advice.
Next step
Data-backed verification before you approve
Whether you're onboarding a borrower or reviewing submitted statements, start with signals, not intuition.