
How to Read a Bank Statement: Every Section Explained
Read a bank statement in six steps: header, period, summary, deposits, withdrawals and fees. With an annotated example and what to check for errors.
To read a bank statement, work from the top down: confirm who and which account it covers, note the statement period, check that the summary balances add up, then review each deposit, withdrawal and fee. The one check that catches most problems is the math: opening balance plus deposits minus withdrawals must equal the closing balance. If you need the basics first, start with what a bank statement is.
While you are here
Catch anomalies before you sign off
Manual PDF review misses things, especially at page 80. DocuClipper's analyzer flags edits, suspicious patterns, and anomalies so your team focuses on the right pages first.
What a bank statement looks like
Every US bank lays its statement out differently, but checking and savings statements carry the same blocks, almost always in this order:
| Section | Where it sits | What it shows | What to check |
|---|---|---|---|
| Bank details | Top of page 1 | Bank name, address, customer service contacts | It is the bank you expect |
| Account holder | Top left of page 1 | Names, mailing address, masked account number | Names and the last four digits match |
| Statement period | Top right of page 1 | Start and end dates of the cycle | No gap from the previous statement |
| Account summary | Page 1 | Beginning balance, total deposits, total withdrawals, fees, ending balance | The math ties out (formula below) |
| Deposits and additions | Following pages | Each credit with date, description, amount | Every deposit has a known source |
| Withdrawals and subtractions | Following pages | Card purchases, ACH debits, checks, transfers | Every debit is yours and expected |
| Fees and interest | Near the end | Service charges, overdraft and NSF fees, interest earned | No surprise or repeated fees |
| Daily balance | Last pages (many banks) | The balance at the end of each day | No unexpected negative days |
Credit card statements use the same idea with different labels: previous balance, payments, purchases, fees, interest and new balance, plus the minimum payment and due date.
The formula behind every statement
Ending balance = previous (beginning) balance + deposits and credits - withdrawals, debits and fees.
If the printed ending balance does not equal that result, a page is missing, a figure was misread, or the document has been altered.
The sections of a bank statement
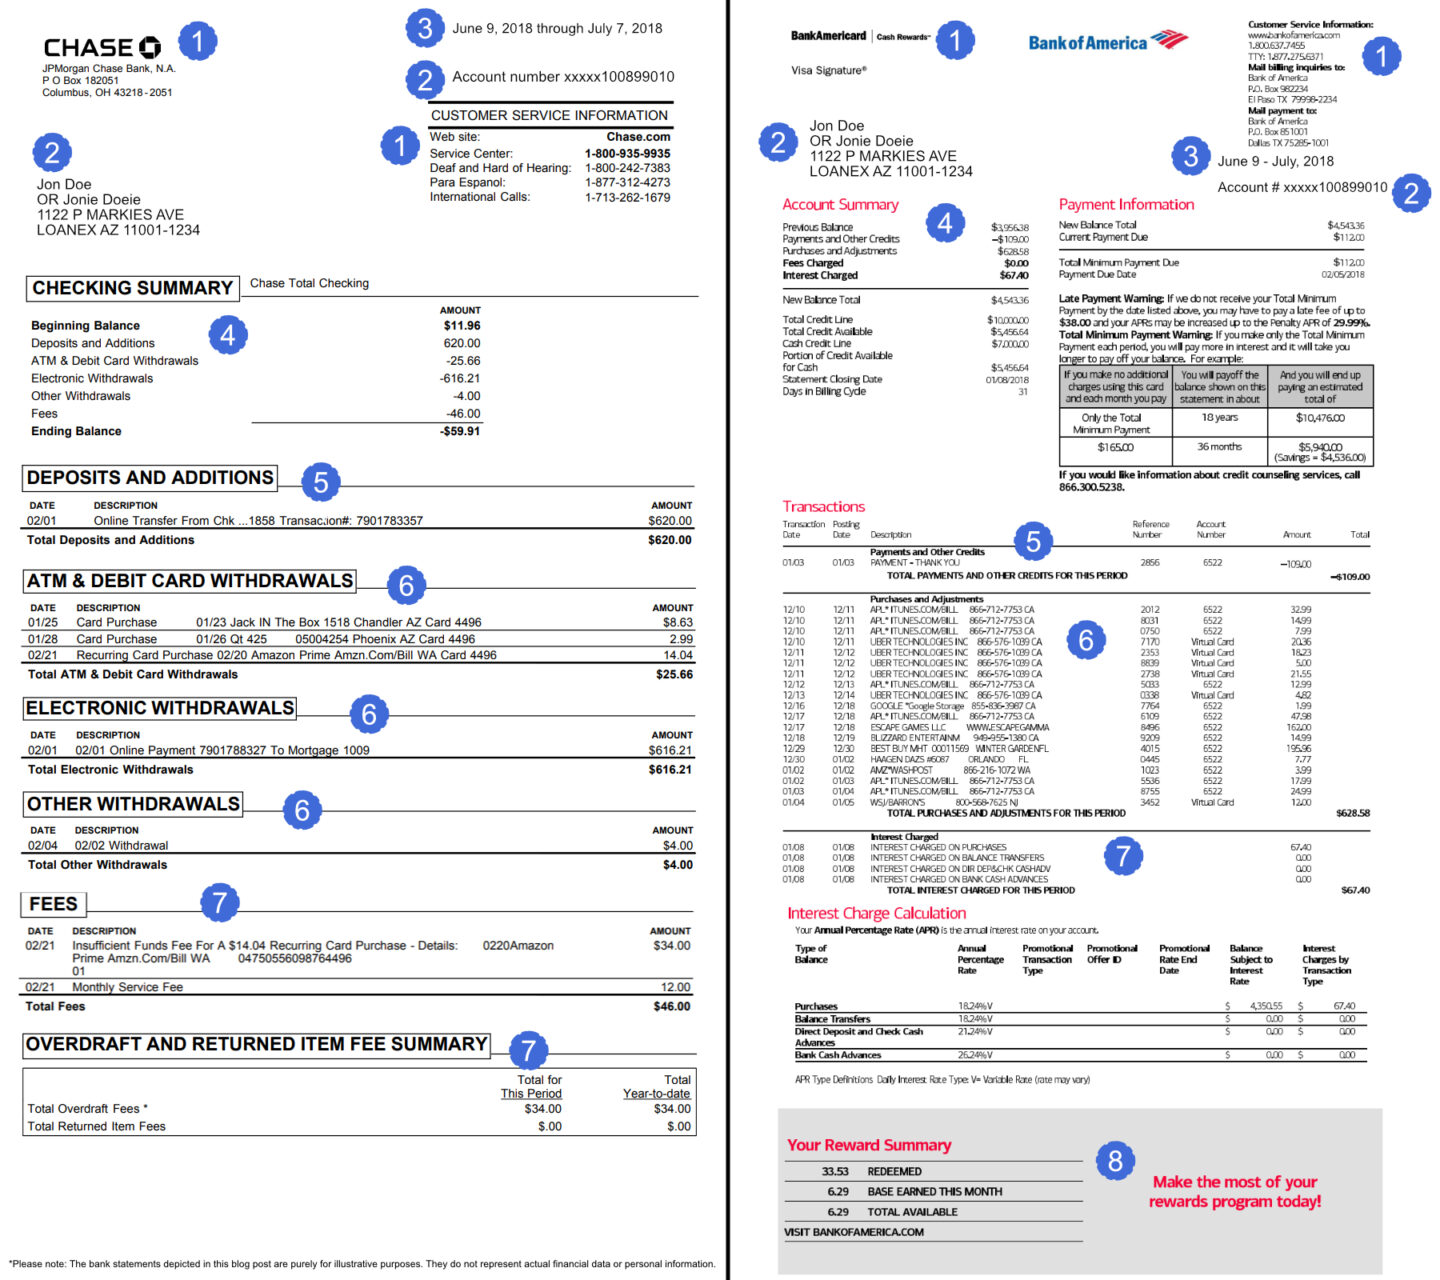
The example below annotates a checking statement (left) and a credit card statement (right). The numbers match the steps that follow.
Step 1: Confirm the header
The header shows the bank's name and customer service contacts (1) and the account holder block with name, mailing address and account number (2). The account number is usually masked to the last four digits.
Primary account holder. On a joint account, the first name printed is generally the primary account holder, and the second line (often starting with "OR" or "AND") is the joint owner. Some banks print both names equally. If you need to know for certain who the primary owner is, for example for a loan file, ask the bank; the statement alone may not say.
Step 2: Check the statement period
The period (3) is printed as a date range, such as "June 9, 2018 through July 7, 2018". It does not always follow calendar months, because banks cycle accounts on different days. When you collect statements for a client or a loan file, line the periods up end to end. A gap between one closing date and the next opening date means a statement is missing.
Step 3: Verify the account summary
The summary (4) is the most useful box on the statement. It shows:
- Beginning balance: the closing balance from the previous statement.
- Deposits and additions: total credits for the period.
- Withdrawals and subtractions: card purchases, electronic withdrawals, checks and other debits.
- Fees: total service charges.
- Ending balance: the balance on the last day of the period.
Do two checks. First, the beginning balance should equal last month's ending balance. Second, beginning balance plus deposits minus withdrawals and fees should equal the ending balance. In the example, $11.96 + $620.00 - $25.66 - $616.21 - $4.00 - $46.00 = -$59.91, which is the printed ending balance. If it does not tie out, something is missing or wrong.
Step 4: Review deposits and credits
Each deposit line (5) has a date, a description and an amount. Descriptions are often shortened, for example "Online Transfer From Chk ...1858" or "ACH Credit Payroll". Match each one to a source you expect: payroll, customer payments, transfers between your own accounts or refunds. Unfamiliar deposits matter too, especially in lending, where unexplained large deposits are a standard underwriting question. For the shorthand banks use, see bank statement abbreviations.
Put it into practice
A checklist only works when nobody's tired
Structured signals give managers a repeatable first pass. Reviewers get consistent results whether they're looking at page 3 or page 300.
Step 5: Review withdrawals and debits
Withdrawals (6) are often grouped by type: ATM and debit card, electronic withdrawals (ACH, bill pay, transfers), checks and other withdrawals. Check card purchases against receipts and recurring charges against subscriptions you actually use. Note the posting date can be a day or more after the purchase date. The bank transactions guide explains each transaction type.
Step 6: Look for fees and interest
The fees section (7) lists monthly service charges, overdraft and NSF (insufficient funds) fees, wire fees and similar charges. Many statements also include a year-to-date overdraft fee summary. Fees to question:
- Monthly maintenance fees you thought were waived by a minimum balance or direct deposit.
- Overdraft or NSF fees, which can repeat when several payments hit an empty account on the same day.
- Out-of-network ATM fees.
- Foreign transaction fees on card purchases.
Interest earned appears as a credit, usually near the end of the statement.
What to do if you find an error
Contact the bank as soon as you spot it. For consumer accounts in the US, Regulation E requires you to report an error on an electronic transfer within 60 days after the bank sends the statement that first shows it. After that, your protection can be limited. Business accounts are not covered by Regulation E, so check your account agreement, which may set a shorter window.
If a statement itself looks wrong (fonts that change mid-page, totals that do not add up, odd formatting), see how to spot a fake bank statement.
Reading a bank statement for a loan, lease or audit
When you read someone else's statements, for a mortgage file, a rental application or a client engagement, the question changes from "is this right?" to "what does this prove?". Underwriters and reviewers read for:
| What to look for | Why it matters | Where it shows up |
|---|---|---|
| Recurring income deposits | Confirms the income on the application | Deposits, usually payroll or ACH credits on a regular cycle |
| Average and lowest balance | Shows whether the account can carry the payment | Daily balance section, or the summary month over month |
| Overdraft and NSF fees | Signals cash-flow stress | Fees section and the year-to-date fee summary |
| Large or unexplained deposits | Standard underwriting condition: source must be documented | Deposits that do not match payroll or a known transfer |
| Transfers between own accounts | Inflate deposits if counted as income | "Online transfer from" lines with matching debits elsewhere |
| Consecutive, complete periods | A missing month can hide activity | Statement periods lined up end to end |
| Balances that tie out | A statement that does not add up may be incomplete or edited | Account summary vs the transaction lines |
Doing that for two or three months by hand is routine. Doing it for every applicant, or for 24 months of business statements, is where a bank statement analyzer earns its place: it groups recurring deposits, pairs transfers between the applicant's own accounts so they are not read as income, lists NSF and overdraft fees by month, and flags months that are missing, statements that do not tie out and PDFs that were edited. For income files, see income verification from bank statements; for rental applications, tenant bank statement verification.
Reading statements at volume
Reading one statement by hand is fine. Reviewing a year of statements for every client account is not. Accountants and bookkeepers use DocuClipper to turn the PDFs into Excel, CSV or QuickBooks files, and every statement is checked against its own printed opening and closing balances, so the ones that do not tie out are flagged before anyone relies on them. More than 115,000 statements a month go through that check, and over 700,000 statements were scored for signs of tampering in the past year. From there, the reconciliation and categorization work happens in a spreadsheet instead of on paper. Start with the bank statement converter or go straight to bank statements to Excel.
FAQ
What are the main parts of a bank statement?
The header (bank and account holder details), the statement period, the account summary with opening and closing balances, the list of deposits and withdrawals, and the fees and interest section.
How do I know who the primary account holder is on a bank statement?
The first name printed in the account holder block is usually the primary owner, and a second name after "OR" or "AND" is a joint owner. Formats vary, so confirm with the bank if it matters.
What formula describes the activity on a bank statement?
Opening balance plus deposits and credits minus withdrawals, debits and fees equals the closing balance.
How long do I have to report a bank statement error?
For US consumer accounts, Regulation E gives you 60 days after the bank sends the statement showing the error to report an electronic transfer error. Business accounts follow the account agreement.
Why does my statement period not match the calendar month?
Banks assign statement cycles to accounts on different days to spread out processing. Your period runs from your cycle date to the day before the next one.
What does a lender look for on a bank statement?
Regular income deposits that match the application, an average balance that supports the payment, overdraft and NSF fees, large or unexplained deposits, transfers between the applicant's own accounts, and complete, consecutive statement periods with no gaps.
Written by the DocuClipper editorial team. Last updated November 2, 2026. General information, not legal or tax advice.
Next step
Data-backed verification before you approve
Whether you're onboarding a borrower or reviewing submitted statements, start with signals, not intuition.